Analysis

The latest Drug Channels commentary — PBMs, 340B, specialty pharmacy, and the contracts that move the money.

Showing 371–380 of 2721

Friday, October 13, 2023

  • Copay Adjustment Programs: What Brand and Hub Teams Need to Know

    Today’s guest post comes from Sam Blake, Vice President of Launch Excellence at ConnectiveRx.

    Sam discusses the evolving landscape of copay adjustment programs. He explains how pharma brand teams and hub program managers can lessen the impact of accumulators and maximizers on patients’ access and adherence.

    To learn more, join Chris Dowd, Senior Vice President of Market Development at ConnectiveRx, for a free webinar on October 26th at 1:00 pm ET: The Battle Over Accumulators and Maximizers: What You Need to Know for 2024.

    Read on for Sam’s insights.

    Posted by Drug Channels Institute, an HMP Global company on Friday, October 13, 2023

    Labels: Guest Post, Sponsored Post

Tuesday, October 10, 2023

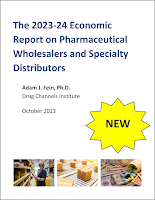
  • NOW AVAILABLE: The 2023–24 Economic Report on Pharmaceutical Wholesalers and Specialty Distributors

    I am pleased to announce our new 2023–24 Economic Report on Pharmaceutical Wholesalers and Specialty Distributors, available for purchase and immediate download.
    We’re offering special discounted pricing if you order before October 23, 2023!

    The 2023–24 Economic Report on Pharmaceutical Wholesalers and Specialty Distributors—our 14th edition—remains the most comprehensive, fact-based tool for understanding and analyzing the large and growing U.S. pharmaceutical distribution industry. No other report on the market today offers the depth, insight and analysis into these channels

    This 2023-24 edition contains the most current financial and industry data along with detailed information about the strategies and market positions of the largest companies: AmerisourceBergen, Cardinal Health, and McKesson. It updates our annual analysis of each wholesaler’s business segments and underlying business profitability, based upon our proprietary economic models.

    The notable new material in this 2023-24 edition includes:
    • New data about commercial pricing and reimbursement for provider-administered biosimilars appears in Section 3.2.2. and Section 6.4.3.
    • A new Section 6.2.2. reviews the evolving specialty pharmacy industry and discusses emerging challenges from direct distribution models that bypass wholesale distribution.
    • A new Section 6.3.2. analyzes the acquisitions of physician practices by corporate entities and private equity firms
    • A new Section 6.5. addresses the Inflation Reduction Act of 2022. In Subsection 6.5.1., we summarize the key provisions of the law that relate to prescription drugs. In Subsection 6.5.2., we analyze the IRA’s likely consequences for wholesalers and the overall pharmaceutical business.
    • We provide updated, expanded, and reorganized data about the following markets:
      • Pharmacy services administrative organizations (Section 2.2.4.)
      • Group purchasing organizations for small pharmacies (Section 2.2.5.)
      • Group purchasing organizations for physician practices (Section 3.3.2.)
    • Material that addresses COVID-19 and its impact on the wholesale channel has been integrated into our analyses throughout the report. However, we have retained and updated Section 6.1.4., which examines the distribution of COVID-19 vaccines and therapeutics.
    • There are 163 exhibits in this 2023-24 edition, compared with 150 in the 2022-23 edition.
    If you would like to pay by corporate purchase order or check, please email Tamra Feldman. If you preordered the report, you should have already received an email with download instructions. Please contact us if you did not receive the email.

    WHAT’S GOING ON


    Twice a year, I research and write two comprehensive, fact-based, and nonpartisan reports on drug channel economics. In some small way, I try to make the world a better and smarter place.

    Licenses for our DCI reports are regularly purchased by nearly every entity involved in the drug channel: pharmaceutical manufacturers, wholesalers, pharmacists, pharmacy owners, hospitals, buyers, benefit managers, managed care executives, policy analysts, investors, consultants, and more. So, you can find out what your customers, partners, and competitors are reading.

    The 2023–24 Economic Report on Pharmaceutical Wholesalers and Specialty Distributors is the only resource of its kind available anywhere. It offers 163 proprietary charts, exhibits, and data tables.

    FOUR FUN FACTS

    • The 9 chapters are self-contained and do not need to be read in order. (Really!) There are loads of internal hyperlinks to help you navigate the document and customize it to your specific interests and priorities.
    • We are offering the option to download an additional PowerPoint file with images of all 163 exhibits. This popular option helps you share the insights and data with others in your organization. (The exhibits appear in all license versions. The PowerPoint file option is available only with the purchase of a corporate license.)
    • There are more than 660 endnotes, most of which have hyperlinks to original source materials. These source materials offer a handy way to build your knowledge base beyond what’s included in the full report.
    • As usual, I have reluctantly stripped out the corny jokes and pop culture references.
    If you have any questions (before or after reading the report), please email me.

    Enjoy!

    Posted by Drug Channels Institute, an HMP Global company on Tuesday, October 10, 2023

    Labels: Industry Trends, Wholesalers, Channel Management

Friday, October 6, 2023

Thursday, October 5, 2023

Wednesday, October 4, 2023

  • Gross-to-Net Bubble Update: 2022 Pricing Realities at 10 Top Drugmakers (rerun)

    This week, I’m rerunning some popular posts while I put the finishing touches on DCI's new 2023-24 Economic Report on Pharmaceutical Wholesalers and Specialty Distributors.

    Click here to see the original post from June 2023.


    Time for Drug Channels’ annual update on pricing at the largest pharmaceutical manufacturers. This year’s review includes the following 10 companies: Eli Lilly and Company, Genentech, GlaxoSmithKline, Janssen, Merck, Novartis, Novo Nordisk, Sanofi, Takeda, and UCB. You can find links to each company’s data below.

    When rebates and discounts were factored in, brand-name drug prices again declined—or grew slowly—in 2022. However, some companies had net price gains. Consistent with our previous analyses, rebates and discounts reduced the selling prices of brand-name drugs at the biggest drugmakers to less than half of their list prices.

    For the eight companies with multiple years of data, the gross-to-net difference in price changes was the smallest gap in six years. See the second chart below.

    As I have noted, powerful industry forces may trigger the gross-to-net bubble to deflate. But for now, the 2022 data provide fresh inconvenient facts for the drug pricing flat earthers (#DPFE).

    Posted by Drug Channels Institute, an HMP Global company on Wednesday, October 4, 2023

    Labels: Gross-to-Net Bubble, Industry Trends, Inflation Reduction Act of 2022, PBMs

Tuesday, October 3, 2023

Monday, October 2, 2023

Friday, September 29, 2023

  • More Than a Feeling: Five Key Challenges When Walking Away From Commercial/340B Duplicate Payments

    Today’s guest post comes from Micah Litow, Chief Operating Officer at Kalderos.

    According to Kalderos, at least 5% of commercial rebates are paid for prescriptions that also have discounts under the 340B Drug Pricing Program. Micah outlines why it's more than a feeling that manufacturers struggle to walk away from these duplicate payments. But as he explains, reliable data is crucial to avoid hearing that old song that PBMs play.

    To learn about Kalderos’ Commercial Discount Monitoring solution, close your eyes and slip away with Micah at his free webinar on November 1, 2023, at 2:00 p.m. ET: Sharpening Focus: How Data Analytics Transforms Commercial Contracting Strategies.

    Read on for Micah’s insights.

    Posted by Drug Channels Institute, an HMP Global company on Friday, September 29, 2023

    Labels: Guest Post, Sponsored Post

Wednesday, September 27, 2023

  • Drug Channels News Roundup, September 2023: PBM Profits, Specialty Rx Markups, CVS Spending Trends, Pharmacy Pricing Secrets, and Deductibles 101

    Autumn is here! Curl up with your favorite pumpkin-spiced blog and savor these stories harvested from the great Drug Channels patch:
    • A must-read report on hidden sources of PBMs’ profits
    • How generic drugs drive specialty pharmacy profits
    • CVS Health’s unadvertised 2022 drug trend report
    • A shocking look at how PBMs set prescription prices
    Plus, Dr. Glaucomflecken teaches us about our insurance benefits.

    P.S. Join my more than 45,000 LinkedIn followers for daily links to neat stuff. You can also find my daily posts at @DrugChannels on Twitter/X, where I have more than 16,900 followers. (I recommend that you follow me on LinkedIn, because the quality of comments and engagement is much higher than they are on Twitter. I’m not posting to Threads yet.)

    Posted by Drug Channels Institute, an HMP Global company on Wednesday, September 27, 2023

    Labels: Generic Drugs, Costs/Reimbursement, Benefit Design, Specialty Drugs, Channel Management, PBMs, Medicare Part D, Pharmacy Economics

Sunday, September 24, 2023

  • EXCLUSIVE: The 340B Program Reached $54 Billion in 2022—Up 22% vs. 2021

    Drug Channels has just obtained new details on the size of the 340B Drug Pricing Program. I couldn’t wait to share the news, hence this special Sunday post.

    For 2022, discounted purchases under the 340B program reached a record $53.7 billion—an astonishing $9.8 billion (+22.3%) higher than its 2021 counterpart. The difference between list prices and discounted 340B purchases also grew, to $52.3 billion (+$2.6 billion).

    Hospitals accounted for 87% of 340B purchases for 2022. Every 340B covered entity type experienced double-digit growth, despite drug prices that grew more slowly than overall inflation.

    Another surprise: HRSA estimated that manufacturers' contract pharmacy restrictions reduced 340B purchases by only $470 million—or less than 1% of 2022's total purchases. That's far below the figure quoted by 340B lobbyists.

    Once again, the data demonstrate that 340B advocates are wrong when they claim that manufacturers are “stripping critical resources from the nation’s health care safety net.” As I noted last year, only in the U.S. healthcare system can billions more in payments and spreads be considered a cut.

    Read on for full details and analysis, including the opportunity to download your own copy of the raw data from HRSA.

    Posted by Drug Channels Institute, an HMP Global company on Sunday, September 24, 2023

    Labels: Gross-to-Net Bubble, Hospitals, 340B, Health Care Policy, Industry Trends, Pharmacy, PBMs